U.S. Sellers: Close in 7 Days Instead of Assigning a Purchase Agreement
An assignable purchase agreement lets a buyer transfer their contractual rights to purchase a property to another party, called the assignee, in exchange for a fee. It transfers equitable interest, not title, and the original buyer often remains legally liable unless the contract or seller grants a release. Whether it’s allowed at all depends on the exact wording in your purchase agreement, your lender’s rules, and your state’s laws.
TL;DR:
- Most purchase agreements are automatically assignable unless explicitly prohibited by the contract, lender, or state law, but check specific clauses carefully.
- The assignment fee is usually paid by the new buyer (assignee) at closing and ranges from $5,000 to $20,000 in typical residential deals.
- Without a formal novation or written release, the original buyer remains liable even after assigning the contract, especially if “with liability” is checked.
- Foreclosure, last-minute financing issues, or title problems frequently cause assignment deals to fall through, so proof of funds and clear communication are essential.
- When significant risks or tight deadlines exist, a direct cash sale may be safer than relying on an assignment, especially if quick closing is required.
Table of Contents
- What Is an Assignable Purchase Agreement?
- How Assignment Works, Step by Step
- Legal Rules and State Differences That Control Assignability
- Assignment vs. Novation: Who Stays Liable?
- Drafting an Assignable Purchase Agreement the Right Way
- Common Risks and Red Flags in Assignment Deals
- A Practical Checklist for Executing an Assignment
- When a Direct Cash Sale Beats Trying to Assign a Contract
- Our Take: The Liability Question Gets Skipped Too Often
- A Faster Path When Assignment Feels Like Too Much Risk
- Sources
- FAQ
What Is an Assignable Purchase Agreement?
An assignable purchase agreement is a real estate contract that permits the buyer, known as the assignor, to hand off their right to purchase a property to a new buyer, the assignee, before closing. The seller stays the same party throughout. What changes is who ultimately closes on the home.
This matters because assignment does not transfer the deed. It transfers a contractual right, what lawyers call equitable interest, meaning the assignee steps into the assignor’s shoes under the original purchase contract but the seller still conveys title directly to whoever ends up closing. The assignor never actually owns the property.
Real estate wholesalers rely on this mechanism constantly. They put a home under contract at a set price, find a buyer willing to pay more, and assign the contract for a fee rather than closing themselves. Assignment fees in residential deals commonly range from $5,000 to $20,000, though the actual number depends on the property’s margin and how motivated everyone is to close fast.
A few core facts define this arrangement:
- The assignor transfers rights under the contract, not ownership of the home itself.
- The assignee typically pays an assignment fee directly to the assignor, separate from the purchase price paid to the seller.
- The seller’s obligations under the original contract carry over unchanged; only the buyer side shifts.
- Assignment is a contract mechanism, not a property conveyance, so it never appears on a deed.
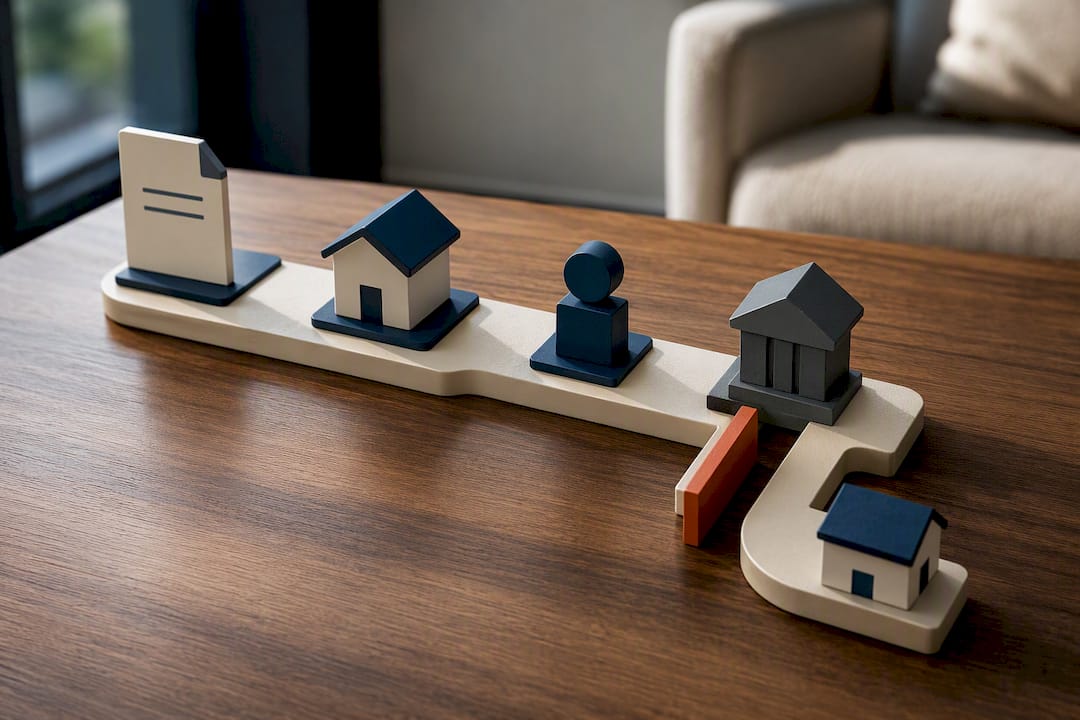
How Assignment Works, Step by Step
Assignment follows a fairly predictable sequence, and knowing the order helps you catch problems before they become expensive ones.
- The original purchase agreement gets signed. This contract between buyer and seller sets price, terms, and closing timeline. Ideally, it already contains assignability language.
- The assignor and assignee sign a separate assignment agreement. This document references the original contract by date and parties, states the assignment fee, and spells out who remains liable if something goes wrong.
- Title or escrow gets notified. The settlement agent needs the assignment agreement on file so the deed and closing documents get prepared in the assignee’s name rather than the original buyer’s.
- The assignee arranges funding and closes. If financing is involved, the lender needs to underwrite the assignee, not the original buyer.
- The assignment fee gets paid, usually at or before closing. It typically shows up as a separate line item on the settlement statement, distinct from the purchase price.
Pro Tip: Earnest money deposited by the original buyer usually needs to transfer to the assignee’s side of the ledger or get refunded before closing. Confirm this with the title company early, not the week of closing.
Financing is where most assignments fall apart. If the assignee can’t secure a loan, or the lender won’t approve a change in borrower after underwriting has started, the deal stalls. Failure to confirm financing for the assignee is one of the most common reasons assignments collapse, leaving the original assignor exposed if they haven’t been released from the contract.
Legal Rules and State Differences That Control Assignability
Contract law starts from a permissive default: agreements are generally assignable unless the contract explicitly says otherwise or the transfer would violate public policy or a specific statute. That default matters, but it doesn’t mean every purchase agreement is silent on the issue. Most standard forms address it directly.
Florida’s widely used FR/BAR contract, for example, gives buyers three explicit choices in its assignability section: assignable without liability, assignable with liability, or not assignable. Whichever box gets checked controls the outcome, and buyers frequently sign without reading that clause closely.
Many states also impose disclosure requirements on wholesalers specifically. Failing to make a required disclosure can allow the seller to cancel the deal before closing, even if the contract itself permitted assignment.
Before you assume a contract can be assigned, check these four things:
- Does the contract contain an explicit assignability clause, and what does it actually say?
- Does financing involve a lender who must approve any change in borrower?
- Is there anti-assignment or change-of-control language buried in boilerplate sections?
- Does your state require specific disclosures for assignment or wholesale transactions?
State law and standard forms vary enough that a clause acceptable in one market may be unenforceable or incomplete in another. When in doubt, have a real estate attorney read the exact language rather than relying on what worked on your last deal.
Assignment vs. Novation: Who Stays Liable?
Assignment and novation sound similar but produce very different legal outcomes, and this is the distinction that trips up more assignors than anything else in this process. Assignment transfers rights to a new party. Novation replaces the original buyer entirely, releasing them from every obligation under the contract.
Legal practitioners repeatedly flag this as the most misunderstood part of the process: many assignors assume signing an assignment agreement automatically frees them from the deal. It doesn’t, unless the paperwork says so or the seller separately agrees to release them.
That’s why the “assignable with liability” versus “assignable without liability” checkbox on standard forms carries real weight. With liability means the assignor stays on the hook if the assignee defaults. Without liability shifts the seller’s remedy to the assignee alone, assuming the seller agreed to that term.
To actually get released, you generally need one of these:
- A negotiated novation, where the seller expressly agrees to substitute the assignee and release the assignor in writing.
- A written seller release, separate from the assignment agreement itself, confirming the original buyer has no further obligation.
- Indemnity language in the assignment agreement, where the assignee agrees to cover the assignor for any losses tied to a default, even if it doesn’t legally release the assignor from the seller.
Pro Tip: Never assume “I assigned the contract” means “I’m out.” Ask for the release in writing, or build indemnity protection into the assignment agreement itself.
Drafting an Assignable Purchase Agreement the Right Way
The cleanest way to avoid disputes later is to build assignability into the contract from day one, not negotiate it after you’ve already found a buyer for your rights.
The most common industry practice is appending “and/or assigns” next to the buyer’s name on the original purchase agreement. This is background practice widely used by wholesalers and investors rather than a formal legal doctrine, and it signals to the seller upfront that assignment may happen, which tends to reduce pushback later. It’s not a legal cure-all. A seller can still negotiate an anti-assignment clause elsewhere in the contract that overrides the intent behind “and/or assigns.”
When drafting or negotiating, aim for these specifics:
- Request an express assignment clause rather than relying on silence or ambiguous boilerplate.
- If the seller objects to the assignment fee being disclosed, address confidentiality directly in the assignment agreement rather than leaving it implied.
- Push for a novation or release clause where the seller is willing to negotiate one, especially on higher-value deals.
- Have a real estate attorney draft or review the assignment agreement. A short, clear document that references the original contract by date and party names is worth the cost.
Get every term in writing. Verbal understandings about liability or fees do not hold up when a deal goes sideways.
Common Risks and Red Flags in Assignment Deals
Assignment deals fail for predictable reasons, and most of them show up before closing if you know where to look.
The biggest structural risks are anti-assignment language buried in the contract, lender refusal to approve the assignee, assignee funding falling through at the last minute, title issues that surface during the transfer, and missed state disclosure requirements for wholesale transactions.
Watch for these red flags in a prospective assignee before you sign anything:
- No proof of funds or pre-approval letter provided, or a refusal to share one.
- Vague or evasive answers about how they plan to close.
- No established relationship with a title company, or reluctance to name one.
Pro Tip: Require proof of funds from the assignee before you sign the assignment agreement, not after. If a deal feels shaky, a double close, where you briefly take title yourself, can protect you from an assignee who fails to perform.
A Practical Checklist for Executing an Assignment
Before you sign anything, confirm the original contract’s assignability language, consider whether “and/or assigns” was included, and check for any lender or state disclosure requirements that apply to your deal.
- Before signing: Review the contract’s assignability clause line by line, and identify whether financing contingencies could block a change in buyer.
- During execution: Sign a written assignment agreement that references the original contract, notify the title or escrow company immediately, and collect proof of funds from the assignee before finalizing anything.
- At and after closing: Confirm the assignment fee appears correctly on the settlement statement, keep signed copies of every document, and retain proof of payment in case a dispute surfaces later.
This sequence protects your legal position at each stage, from signature to final payout.
When a Direct Cash Sale Beats Trying to Assign a Contract
Assignment works best when you have time, a reliable assignee lined up, and a property that’s easy to remarket. If you’re facing foreclosure, a tight timeline, or a home that needs real repairs, chasing an assignee introduces risk you may not have room for.
One trusted company has spent over 16 years helping Metro Detroit homeowners skip that uncertainty entirely. Instead of finding and vetting an assignee, sellers can get a fair, all-cash offer quickly and close in as little as seven days, as-is, with no repairs, no cleaning, and no financing contingency to fall through.
- No lender approval needed, since there’s no assignee financing to underwrite.
- No risk of an assignment falling apart because a buyer’s proof of funds turns out to be false.
- A faster path for owners dealing with inherited property, disrepair, or financial hardship.
Our Take: The Liability Question Gets Skipped Too Often
Most explanations of assignable purchase agreements focus almost entirely on the mechanics, how to write the clause, how the fee gets paid, when title changes hands. What gets glossed over is the liability question, and that’s the part that actually determines whether assignment was a smart move or an expensive mistake six months later.
The conventional advice treats “assignable” as a yes-or-no contract feature. It isn’t. It’s a spectrum that runs from full liability retention to a clean novation release, and the checkbox a buyer picks at signing, often without a second thought, decides which end of that spectrum they land on. If we had one prioritization to offer, it’s this: negotiate the liability question before you negotiate the fee. Investors chase the biggest assignment fee and treat the liability clause as boilerplate, then get surprised when an assignee defaults and the seller comes after them anyway.
For sellers weighing whether to accept an assignable offer at all, that same liability gap is worth understanding, since it affects how reliably the deal actually closes.
— Real Estate Team
A Faster Path When Assignment Feels Like Too Much Risk
Sell Dave Your House gives Metro Detroit sellers a way to skip the assignment process entirely, no waiting on an assignee’s financing, no liability clauses to negotiate, no risk that a buyer’s proof of funds falls through at the last minute.
If you’re facing foreclosure, an inherited property you don’t want to manage, or a home that needs more repairs than you can afford, a direct cash sale removes the moving parts that make assignment deals risky. A cash home buying service can provide a fair, all-cash offer quickly, cover standard closing costs, and close in as little as seven days, all without requiring repairs or cleanup. For a deeper look at how this compares to a traditional closing timeline, see this seller’s guide to cash sale closing.
If your situation calls for speed and certainty over chasing an assignee, get a fair cash offer and see your numbers within 24 hours.
This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.
Sources
- Law Cornell — Assignment
- Understanding Assignability of Contract — Florida Realtors
- Assignments of Contracts in Florida Real Estate — Berlin Patten Ebling
- What Is a Wholesale Real Estate Assignment Contract? — LegalClarity
FAQ
Can a purchase agreement be assigned?
Yes, in most cases. Purchase agreements are assignable by default under general contract law unless the contract specifically prohibits it or a lender or state law blocks the transfer.
What is an assignable purchase contract?
It’s a purchase agreement that allows the original buyer, the assignor, to transfer their contractual right to buy the property to a new buyer, the assignee, typically in exchange for an assignment fee.
Is assignment of contract legal in Florida?
Yes. Florida’s standard FR/BAR contract explicitly addresses assignability, letting parties choose whether a deal is assignable without liability, assignable with liability, or not assignable at signing.
Who pays the assignment fee?
The assignee, the new buyer taking over the contract, typically pays the assignment fee to the assignor. It usually appears as a separate line item on the closing settlement statement rather than being folded into the purchase price.
Does assigning a contract release the original buyer from liability?
Not automatically. Assignment alone does not release the assignor unless the contract specifies “without liability” or the seller grants a separate written release or novation.